Quick answer: Original Medicare is federal health insurance offering nationwide flexibility to see any provider without referrals. Medicare Advantage is an alternative run by private insurers that bundles hospital, medical, and usually drug coverage into one plan, often adding extra benefits but requiring you to use a specific provider network.
When choosing between Original Medicare and Medicare Advantage, the decision comes down to whether you prioritize maximum flexibility in choosing doctors or a bundled plan with extra benefits and an out-of-pocket spending limit. This guide breaks down how both options work, what they cost, and how to pick the right path for your everyday healthcare needs.
What is the difference between Original Medicare and Medicare Advantage?
Original Medicare is the federal government’s own health insurance, made up of Part A (hospital insurance) and Part B (medical insurance). It covers inpatient hospital stays, skilled nursing, hospice, doctor visits, outpatient care and preventive services, and you can use any doctor or hospital that takes Medicare, anywhere in the U.S.
Medicare Advantage (Part C) is the alternative: plans run by Medicare-approved private insurers that bundle Part A and Part B, and usually Part D drug coverage, into one plan. They may add benefits Original Medicare doesn’t cover, such as routine dental, eye or hearing care, but you may need to use doctors and other providers in the plan’s network for non-emergency care.
How do costs and coverage compare?
With Original Medicare you pay the Part B premium and then usually 20% of the Medicare-approved amount for most Part B services, and there’s no yearly limit on what you pay out-of-pocket unless you have supplemental coverage such as Medigap. Medicare Advantage plans set their own premiums, deductibles and copays, but every plan has a yearly limit on what you pay for covered services.
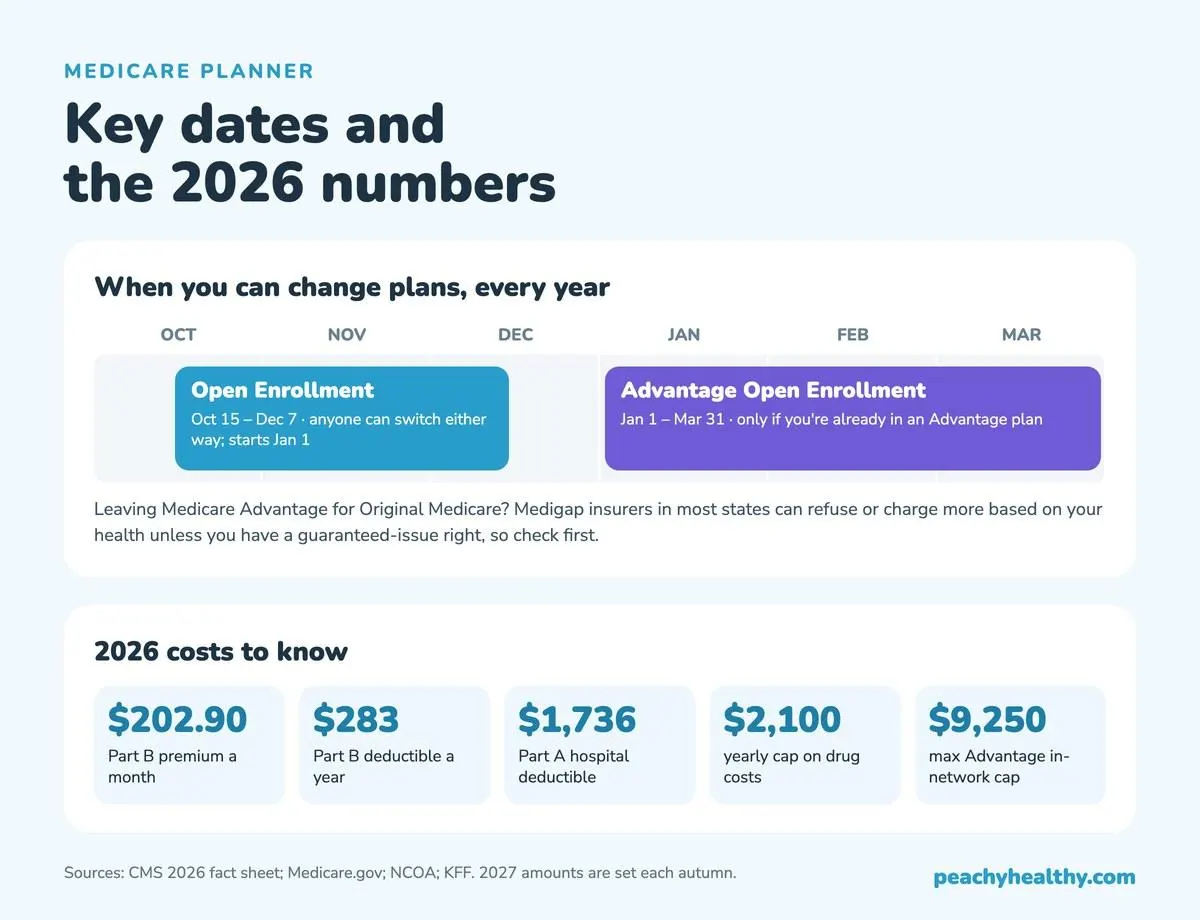
The 2026 figures from CMS: the standard Part B premium is $202.90 a month and the Part B deductible is $283. The Part A hospital deductible is $1,736 per benefit period, and about 99% of people pay no Part A premium because they or a spouse paid Medicare taxes for long enough. For Medicare Advantage, the 2026 cap on in-network spending can be as high as $9,250, and many plans set it lower. Prescription costs have their own cap: once you’ve spent $2,100 out of pocket on covered drugs in 2026, you pay nothing more for them that year, whether your drug coverage is a standalone Part D plan or part of an Advantage plan. CMS announces the following year’s amounts each autumn.
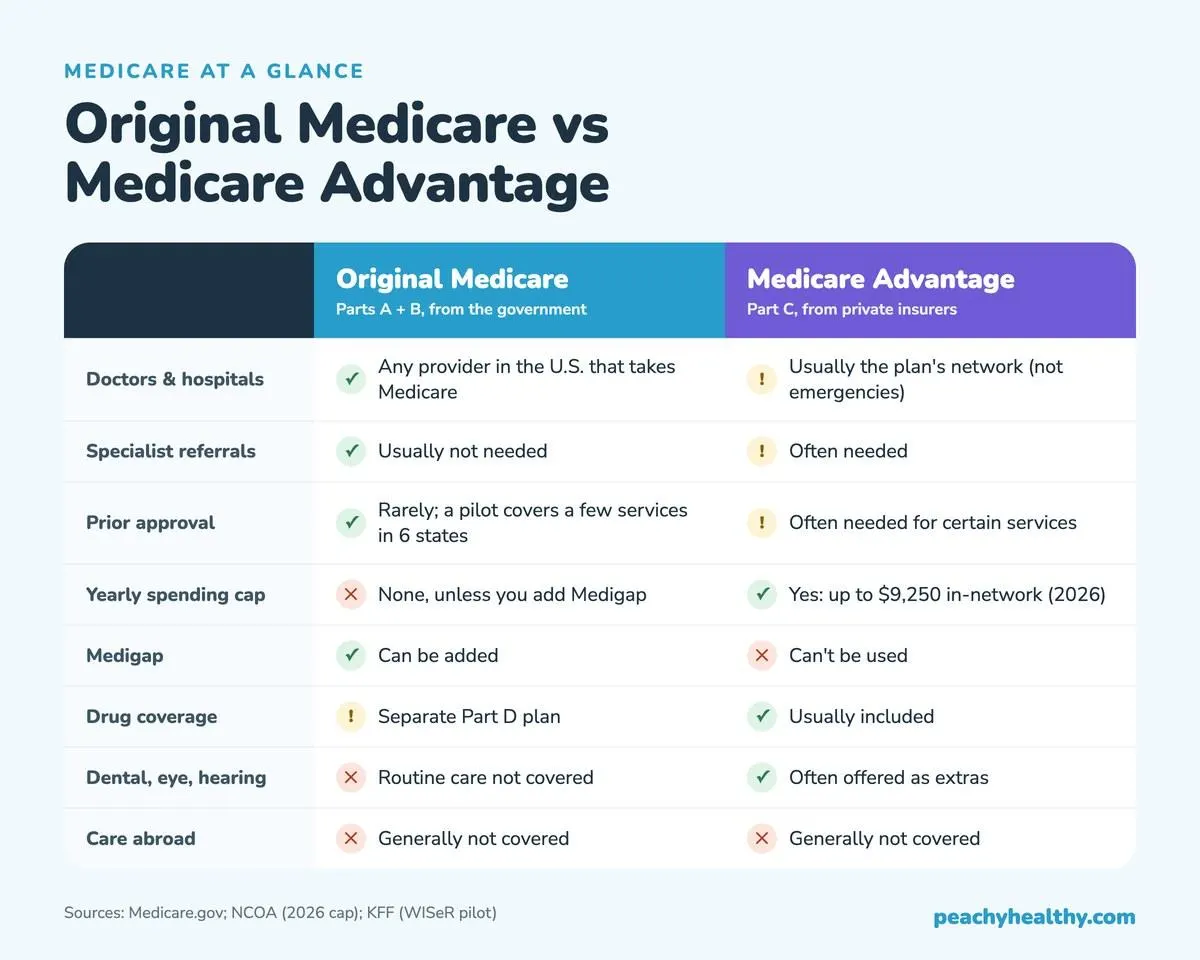
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Doctors and hospitals | Any provider in the U.S. that takes Medicare | Usually the plan’s network, except emergencies |
| Referrals to specialists | Usually not needed | Often needed |
| Prior authorization | Usually not needed (a pilot adds it for a few services in six states) | Often needed for certain services |
| Yearly out-of-pocket limit | None, unless you add Medigap | Yes; up to $9,250 in-network in 2026 |
| Medigap | Can be bought | Can’t be used |
| Prescription drugs | Separate Part D plan | Usually included |
| Routine dental, vision, hearing | Not covered | Often included as extras |
| Care outside the U.S. | Generally not covered | Generally not covered |
Which plan offers the right doctor network for you?
If you travel often, spend winters in another state, or want to keep seeing particular specialists, Original Medicare gives the widest choice: any provider nationwide that takes Medicare, and in most cases no referral.
Medicare Advantage works more like private insurance. You’ll usually use the plan’s network, may need a referral to see a specialist, and may need prior authorization from the plan before it covers certain services or supplies. Before you join one, check that your doctors, hospital and pharmacy are in its network.
Original Medicare is starting to use prior authorization in a small way too. Since January 2026, a CMS pilot called WISeR has required approval for a short list of services in Arizona, New Jersey, Ohio, Oklahoma, Texas and Washington, including skin substitutes for chronic wounds, epidural steroid injections and electrical nerve stimulator implants. Elsewhere, Original Medicare rarely asks for approval in advance.
What happens if I need prescription drug coverage?
With Original Medicare, drug coverage comes from a separate Part D plan. Joining one when you’re first eligible is worth doing even if you take few medicines now, because going without creditable drug coverage can mean a late enrolment penalty added to your premium for as long as you have Part D.
Most Medicare Advantage plans include drug coverage, so you don’t need a separate Part D plan. Either way, the $2,100 yearly cap on out-of-pocket drug costs applies in 2026. One trade-off to remember: if you’re in Medicare Advantage, you can’t buy Medigap to cover your out-of-pocket costs.
Practical steps for choosing your plan
AI illustration · Peachy Healthy
Medicare’s Open Enrollment runs from October 15 to December 7 every year, with changes taking effect on January 1. Use this checklist before you decide:
Medicare Plan Checklist
- Check your doctors: Confirm they accept Medicare, and whether they’re in any Advantage plan’s network you’re considering.
- List your medicines: Check each one is on the plan’s drug list (formulary), and at what cost.
- Add up the total cost: Premium, deductibles, copays and the out-of-pocket maximum, not just the monthly premium.
- Think about travel: Spending time in another state favours Original Medicare’s nationwide coverage.
- Check the rules: Ask whether you’ll need referrals or prior authorization for the care you use most.
- Plan for Medigap: If you might want Original Medicare plus Medigap later, check your guaranteed-issue rights first.
- Mark the dates: October 15 to December 7 for changes; January 1 to March 31 if you’re already in an Advantage plan.
Frequently asked questions
Why do people choose original Medicare over Medicare Advantage?
People typically choose Original Medicare for its nationwide flexibility. It allows you to see any specialist who accepts Medicare without needing referrals or prior authorizations, which is ideal for those with complex health needs or who travel frequently.
What are the disadvantages of Medicare Advantage over regular Medicare?
The main disadvantages are network restrictions and prior authorization requirements. You must use in-network providers for non-emergency care, and the plan may require approval before covering certain services. Additionally, you cannot purchase a Medigap policy to cover out-of-pocket costs if you are enrolled in Medicare Advantage.
Can I switch back onto regular Medicare and cancel Medicare Advantage?
Yes, you can switch back to Original Medicare. You can make this change during Open Enrollment (October 15 to December 7), or, if you’re already in an Advantage plan, during the Medicare Advantage Open Enrollment Period (January 1 to March 31). If you switch back you can also join a standalone Part D plan. Medigap is the catch: outside protected situations, such as leaving an Advantage plan within the first 12 months after joining it when you first became eligible, insurers in most states can refuse to sell you a Medigap policy or charge more based on your health. Check your rights before you drop an Advantage plan.